Gateway/Services/Insurance claims assistance
Water damage insurance
claim help in St. Louis.
A claim may require additional information about the loss, policy or proposed repairs. Gateway can organize restoration photographs, moisture observations and an itemized scope for review. Documentation does not guarantee approval or a particular completion date.
Same operators as AirSense Environmental 145+ five-star reviews for sister company AirSense Owner IICRC WRT + ASD certified
Why claims actually stall
Why do water damage
insurance claims get denied?
A claim may require additional information about the loss, policy or proposed repairs. Gateway can organize restoration photographs, moisture observations and an itemized scope for review. Documentation does not guarantee approval or a particular completion date.
Why scope format gets a water damage claim rejected
Ask the claim representative which estimate format and supporting details are required. An itemized scope can describe quantities and proposed work; no format automatically approves or rejects a claim.
What documentation a water damage claim needs
Keep available moisture observations, photographs, equipment records and material notes with the claim file. Ask the insurer what additional documentation is needed.
Why mismatched line items stall a claim
Explain the reasons for proposed removal, drying duration and equipment use. The insurer may ask questions or request more information; a mismatch does not establish an automatic supplement or fixed delay.
“We treat restoration documentation as part of the job. The insurer still determines coverage and reviews the proposed scope.”
What’s included
What every water damage
insurance file includes
-
Why Xactimate-aligned pricing matters on a claim
Itemized quantities and proposed costs should reflect the actual work and materials. Confirm any estimate-format requirements with the insurer.
-
Daily moisture-reading logs
Keep available moisture observations and monitoring dates with the restoration record. Confirm the project’s drying objectives and monitoring schedule.
-
Equipment counts & run-time
Record the equipment used and available operating records for the agreed work.
-
Before / during / after photo set
Photograph affected materials and work progress when safe. Images support scope review without guaranteeing approval.
-
Cause-of-loss documentation
Source identified and photographed. Plumber report attached when applicable. Timeline of events for the carrier’s records.
-
Adjuster communication (with your authorization)
With your authorization, discuss restoration records with the claim representative. Confirm communication arrangements; a direct conversation does not guarantee faster review.
-
Supplemental request handling
When the initial scope doesn’t cover something the work uncovered (hidden mold, deeper saturation than expected), we file the supplemental, with the documentation to support it, instead of leaving you to argue with the carrier.
-
Final closeout package
Confirm which closeout records will be supplied, including available scope, photographs, drying records and any independent reports relevant to the work.
Water damage claim documentation starts during mitigation.
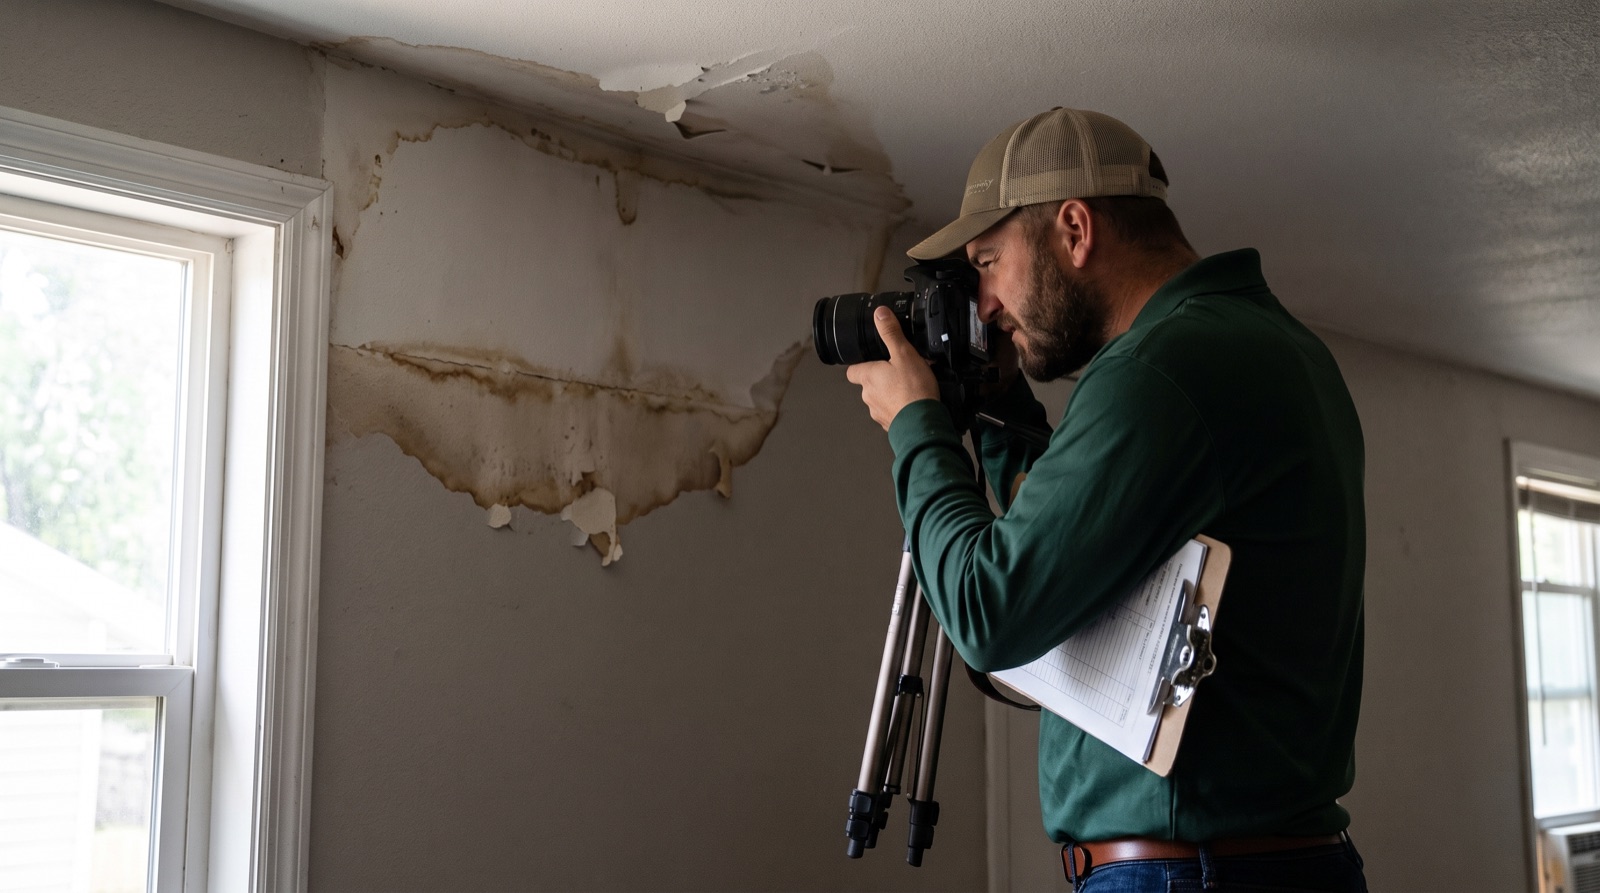
The best insurance file is built while the water damage work is happening, not after the rooms are dry. Photos, moisture readings, source notes, category of water, affected materials, equipment placement, and daily drying logs all help show the carrier what happened and why the mitigation scope was necessary.
Gateway Water & Mold connects the field work to the claim file from day one. If your loss starts with emergency water extraction, we document standing water, affected rooms, and the first moisture readings before drying equipment is placed. If the damage spreads into walls, flooring, cabinets, or subfloor, the file carries forward into full water damage restoration documentation.
What the adjuster needs to see
- Source of loss and whether it was sudden, ongoing, clean water, gray water, or contaminated water.
- Photos of affected rooms, materials, baseboards, flooring, cabinets, ceilings, and contents when relevant.
- Moisture readings before drying, during drying, and at completion.
- Mitigation actions taken quickly to prevent secondary damage and mold growth.
- Final scope notes that explain what dried in place, what was removed, and why.
That documentation does not guarantee coverage, but it gives the carrier a clean file to review and gives you a stronger basis for the scope if questions come up.
How the file flows
The four phases of a water damage insurance claim
-
01
Initial water damage scope and estimate
Agree on the estimate delivery timetable and authorize any submission to the insurer.
-
02
Mid-job water damage documentation
Daily logs added to the file as work progresses. Adjuster gets visibility into the in-progress mitigation if they want it.
-
03
The water damage claim closeout file
Final scope, all photos, all logs, completion certificate. Delivered as a single PDF the adjuster can review in one sitting.
-
04
Water damage claim approval and payment
The insurer reviews the submitted file and determines coverage and payment under the policy. Confirm the decision, timing and any repair authorization before proceeding.
How it works on your end
What paperwork do you need from
me for a water damage claim?
Confirm work authorization and permission for Gateway to communicate about restoration records. The insurer may still need information or decisions directly from you. Contractor documentation does not replace the policyholder’s claim obligations.
Confirm work authorization and permission for Gateway to communicate about restoration records. The insurer may still need information or decisions directly from you. Contractor documentation does not replace the policyholder’s claim obligations.
- Signed authorization to communicate with your adjuster
- Signed work authorization for the mitigation scope
- We handle: scope, photos, logs, supplementals, closeout file
- You handle: deciding things only you can decide (rebuild scope, etc.)
Common questions
Common questions about
water damage insurance claims
Do you bill the insurance directly?
Payment routing requires the applicable authorization and carrier arrangements. Confirm who receives payment and any deductible, limits or uncovered work; direct billing does not mean the owner owes only the deductible.
What if my carrier denies part of the scope?
Additional restoration records may support a requested scope review. Ask the insurer to explain its decision; a supplement does not guarantee approval or establish why the original item was declined.
What is Xactimate, and why does it matter?
Xactimate is a line-item estimating tool used to describe repair quantities and costs. Confirm the format required by your insurer. The software does not determine coverage or guarantee a faster decision.
Do you do public adjusting?
Gateway acts as a restoration contractor, not a public adjuster. A contested claim may require an appropriately licensed public adjuster or attorney, depending on the issue.
What if I already filed and the adjuster gave me a number?
We can compare the documented restoration needs with the existing estimate and provide supporting records for any requested revision. No percentage shortfall or additional payment is assumed.
Will my premiums go up after a claim?
Premium and renewal effects depend on the insurer, policy and underwriting circumstances. Ask your agent or insurer about your specific situation; a single claim does not have a predictable universal effect.
What should I avoid saying to an insurance adjuster about water damage?
Stick to what you know. Don’t guess how long a leak has been going on or what caused it, because words like “slow” or “for a while” can be read as gradual damage, which many policies exclude. Describe what you saw and when, and let the moisture readings, photos and our documentation show the rest. Be honest; never misstate facts.
How long does a water damage claim stay on my insurance record?
Claims are usually reported to the CLUE database, which insurers check when you buy or renew a policy, and records typically stay there for up to seven years. Ask your insurer or agent how a specific claim may affect your premium.
Does my home insurance cover a leaking pipe?
It depends on your policy and on how the leak happened, and your insurer decides coverage. Many homeowners policies cover sudden and accidental water damage, such as a pipe that bursts. Many also exclude damage from a slow leak that went on over time or from wear and tear. The pipe itself may be treated differently from the damage it caused. Gateway documents the source, moisture readings and photos so your adjuster has a clear record to review.
What’s the biggest mistake people make when dealing with an insurance claim?
One of the most common mistakes is waiting. Waiting to report the loss or to start drying can let the damage spread, and many policies expect you to take reasonable steps to stop more damage. Another mistake is throwing out damaged materials before anyone photographs and documents them. Gateway documents the source, moisture readings and photos so the adjuster can see what happened. Read your policy, keep copies of everything, and remember that your insurer decides coverage. For legal questions about a claim, talk to an attorney.
Related services
What else we do.
Water damage and mold claim documentation checklist
Use this checklist to organize your conversation with the adjuster. Coverage depends on your specific policy, endorsements and loss circumstances; confirm requirements with your carrier.
- Find your policy number, declarations page and relevant endorsements. Record the carrier contact and claim number once assigned.
- Record when you discovered the damage, the suspected source and the affected rooms. Keep a dated timeline of events and conversations.
- When safe, photograph the damage and affected belongings before cleanup. Keep original files and avoid entering unsafe areas for pictures.
- Keep receipts and records for emergency mitigation, drying equipment, temporary repairs and other related expenses.
- Request the inspection findings, moisture readings, drying logs, itemized scope and invoices from the restoration team.
- Ask the adjuster what additional documentation is required and what decisions need approval. Keep their written responses with your claim records.
Documentation supports review; it does not guarantee coverage or a payment timeline. Gateway can help organize your restoration records through insurance claims assistance. For emergency help, call (314) 207-9807, 24/7.
Claims help by city
Insurance-claims help, by neighborhood.
Xactimate scopes, drying logs, adjuster coordination. Local knowledge per city, per carrier. Pick your city.
Inner Ring
West County
North County
South County
St. Charles County
City of St. Louis
Illinois Riverbend
Metro East
Belleville Cluster
Already filed and stuck?
We can step in mid-claim. Live phone, twenty-four seven.
Content timestamped by ScoreDetect. View certificate
Related service information
Read about insurance claims assistance in Clayton, MO and the local property conditions that shape the work.
Read about insurance claims assistance in Chesterfield, MO and the local property conditions that shape the work.
Read about insurance claims assistance in St. Louis City, MO and the local property conditions that shape the work.
Read about insurance claims assistance in Florissant, MO and the local property conditions that shape the work.
Read about insurance claims assistance in Edwardsville, IL and the local property conditions that shape the work.
Read about insurance claims assistance in Belleville, IL and the local property conditions that shape the work.
Check our complete Missouri and Illinois service area for additional communities.