Gateway/Insurance/Erie Insurance/Appliance Leak Claim
Erie Insurance
Appliance Leak Claim.
How Gateway handles Erie Insurance appliance leak water damage claims in the St. Louis metro. Carrier-specific documentation, scope, and claim-payment questions.
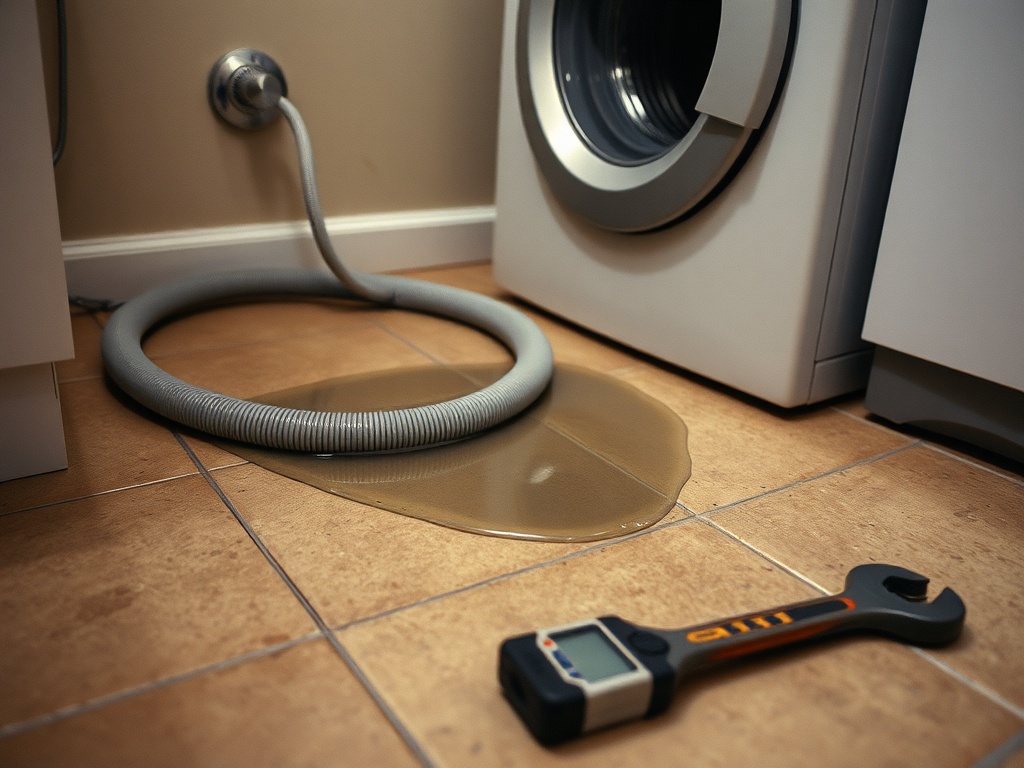
For an appliance loss, retain the appliance details, observed failure point and discovery timeline. Ask Erie how the actual policy applies to the hose, tank or appliance failure and any resulting mold. Do not assume a dispatch deadline, invoice-review rule or standard mold limit.
How Erie handles appliance leak claims
Confirm the assigned adjuster, estimate requirements, payment recipients and billing arrangements for this loss. Erie’s homeowner guidance explains that the policyholder chooses and authorizes the contractor. Do not assume a particular network, estimating price list, direct-billing route or settlement window applies to Gateway work.
Coverage questions on an Erie Insurance appliance leak claim
Ask the adjuster to explain any disputed cause or estimate item with the applicable policy or review requirement. Keep failure-point photographs, appliance details and shutoff information with the scope. No particular denial pattern or guaranteed invoice treatment is established.
What Gateway documents differently on an Erie Insurance appliance leak claim
For an appliance loss, keep the ID plate, failure-point photographs, supply-line condition, shutoff time and observed wet boundary with the estimate. Identify any mold work separately and ask Erie about applicable coverage and estimate requirements; do not size the scope to an assumed national cap.
Will Erie cover a washer hose burst?
A washer-hose failure must be reviewed against the actual policy and facts. Photograph the failure point and record how and when water was discovered. Ask the adjuster to identify the applicable coverage, exclusions and deductible before treating the work as payable.
How much will Erie pay for mold from an appliance leak?
Ask Erie to identify the mold coverage, exclusions and limit in the actual policy and endorsements. Do not rely on a generally quoted $10,000 amount or assume a covered water event pays every mold-remediation item.
Why does Erie adjust mitigation invoices on review?
Describe the work and supporting moisture records clearly in the appliance-loss estimate. Ask the adjuster which items require clarification; standards-based documentation does not guarantee a particular invoice outcome.
Water damage and mold claim documentation checklist
Use this checklist to organize your conversation with the adjuster. Coverage depends on your specific policy, endorsements and loss circumstances; confirm requirements with your carrier.
- Find your policy number, declarations page and relevant endorsements. Record the carrier contact and claim number once assigned.
- Record when you discovered the damage, the suspected source and the affected rooms. Keep a dated timeline of events and conversations.
- When safe, photograph the damage and affected belongings before cleanup. Keep original files and avoid entering unsafe areas for pictures.
- Keep receipts and records for emergency mitigation, drying equipment, temporary repairs and other related expenses.
- Request the inspection findings, moisture readings, drying logs, itemized scope and invoices from the restoration team.
- Ask the adjuster what additional documentation is required and what decisions need approval. Keep their written responses with your claim records.
Documentation supports review; it does not guarantee coverage or a payment timeline. Gateway can help organize your restoration records through insurance claims assistance. For emergency help, call (314) 947-3419, 24/7.
More Erie Insurance resources
Other Erie Insurance pages
on Gateway.
Erie Insurance appliance leak claim. Call now.
Call Gateway, twenty-four seven, to describe the loss and confirm current crew availability and the next response step.
Policy and process sources (reviewed 2026-09-10): ei-prd-fe.erieinsurance.com; ei-prd-fe.erieinsurance.com. Coverage and claim handling depend on the applicable policy, endorsements and loss circumstances.