USAA distinguishes sudden accidental water damage from flood damage, which requires separate flood protection. Record the actual route water took into the property and ask USAA which policy applies. Do not treat every basement loss as flood damage or assume NFIP is the only possible flood insurer.
How USAA handles storm and heavy rain claims
USAA’s claims FAQ allows members to choose their contractor. Provide the available loss photographs, repair estimate and requested records, then confirm any further inspection, payment and timing requirements with the assigned claim handler.
Common denial reasons on a USAA storm and heavy rain claim
Describe the observed failure or entry point, discovery time and any known earlier damage accurately. If USAA denies coverage, request the written explanation and cited policy language. Photographs and repair records can support review but cannot override an exclusion or prove a loss date by themselves.
What Gateway documents differently on a USAA storm and heavy rain claim
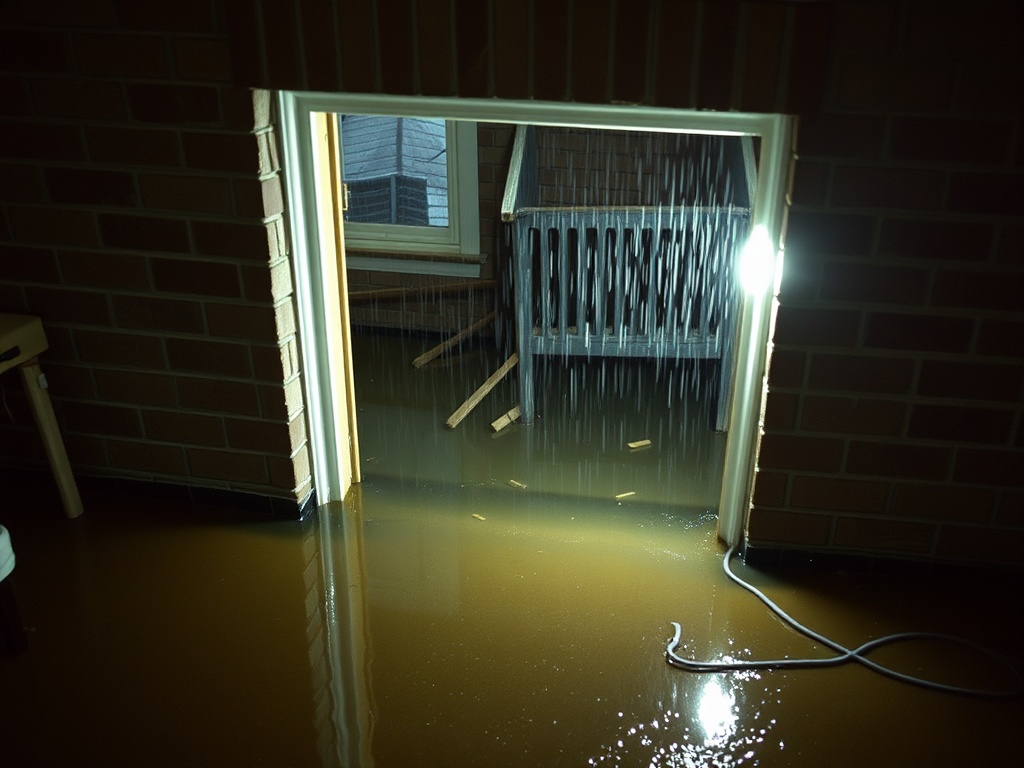
For storm damage, keep available photographs of the observed entry point and damage path, along with the discovery timeline and any relevant weather records. State what the evidence establishes and what remains uncertain. Ask USAA whether a separate flood policy may be involved.
Will USAA cover flood damage from a storm?
USAA distinguishes sudden accidental water damage from flood damage, which requires separate flood protection. Record the actual route water took into the property and ask USAA which policy applies. Do not treat every basement loss as flood damage or assume NFIP is the only possible flood insurer.
How does USAA handle wind/hail deductibles in MO and IL?
Review the declarations and endorsements for the deductible that applies to this storm loss. Ask USAA to explain any percentage-based calculation before estimating recovery.
Will USAA pay for mold from a storm leak?
USAA says its homeowners policy may provide limited mold protection when a covered water loss caused the damage. Gradual damage and flooding are generally outside the described coverage. Ask USAA which policy terms, limits and endorsements apply to the particular mold loss.
Water damage and mold claim documentation checklist
Use this checklist to organize your conversation with the adjuster. Coverage depends on your specific policy, endorsements and loss circumstances; confirm requirements with your carrier.
- Find your policy number, declarations page and relevant endorsements. Record the carrier contact and claim number once assigned.
- Record when you discovered the damage, the suspected source and the affected rooms. Keep a dated timeline of events and conversations.
- When safe, photograph the damage and affected belongings before cleanup. Keep original files and avoid entering unsafe areas for pictures.
- Keep receipts and records for emergency mitigation, drying equipment, temporary repairs and other related expenses.
- Request the inspection findings, moisture readings, drying logs, itemized scope and invoices from the restoration team.
- Ask the adjuster what additional documentation is required and what decisions need approval. Keep their written responses with your claim records.
Documentation supports review; it does not guarantee coverage or a payment timeline. Gateway can help organize your restoration records through insurance claims assistance. For emergency help, call (314) 947-3419, 24/7.
More USAA resources
Other USAA pages
on Gateway.
USAA storm and heavy rain claim. Call now.
Call Gateway, twenty-four seven, to describe the loss and confirm current crew availability and the next response step.
Policy and process sources (reviewed 2026-09-10): mobile.usaa.com; www.usaa.com. Coverage and claim handling depend on the applicable policy, endorsements and loss circumstances.