Gateway/Insurance/American Family/Storm and Heavy Rain Claim
American Family
Storm and Heavy Rain Claim.
How Gateway handles American Family storm and heavy rain water damage claims in the St. Louis metro. Carrier-specific documentation, scope, and claim-payment questions.
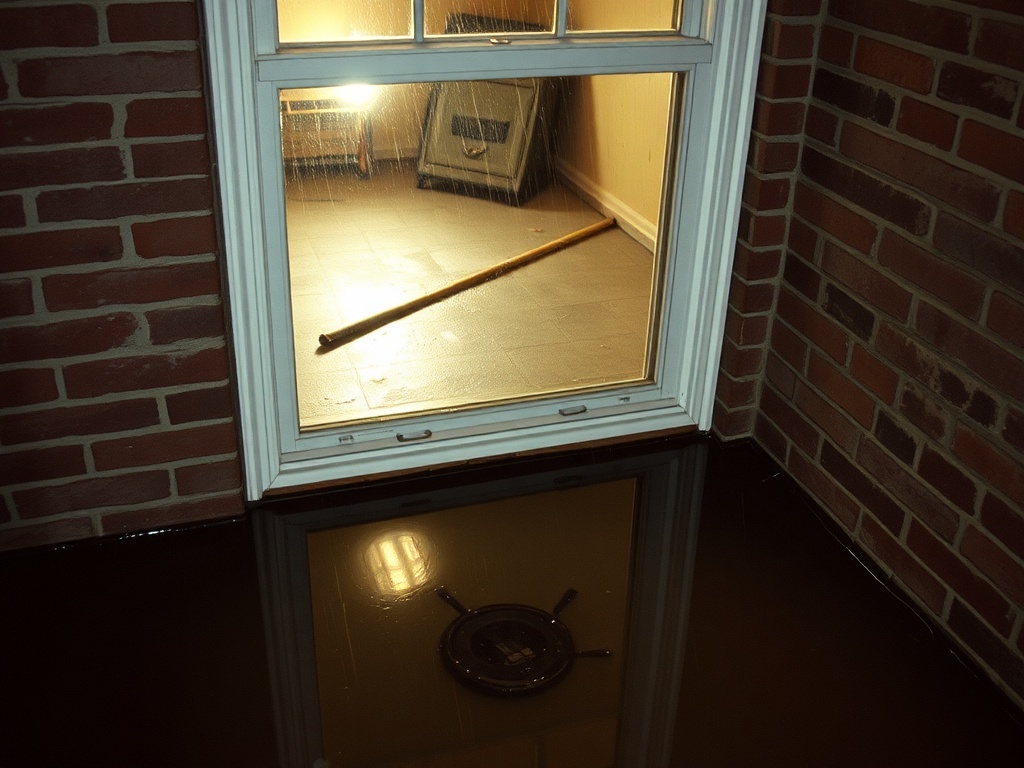
For storm-related water damage, identify the entry point and ask American Family which policy provisions apply. Wind-driven rain, surface water and sewer backup can raise different coverage questions. Check the endorsements and any wind/hail deductible shown on the declarations page instead of assuming a rule applies across all Missouri and Illinois ZIP codes.
How American Family handles storm and heavy rain claims
Ask the assigned adjuster about inspection requirements, estimate review and the next claim update. American Family publishes an Emergency Water Removal Program, but that does not establish Gateway’s participation. Confirm billing arrangements before authorizing work and request a claim-specific timeline from the assigned adjuster.
Coverage questions on an American Family storm and heavy rain claim
Document the water entry point, damaged assemblies and any pre-existing roof or moisture issues. If the carrier questions coverage, request the specific policy language and its explanation of the cause-of-loss decision. Avoid assuming that every storm loss has the same exclusion or denial outcome.
What Gateway documents differently on an American Family storm and heavy rain claim
Keep dated photos, available storm records and observations of the water path with the restoration scope. Describe wind-driven rain, surface intrusion and any sewer or sump component separately. Let the carrier determine which policy provisions apply rather than labeling work covered or excluded before review.
Does American Family cover sewer backup during a storm?
Check for backup coverage and ask American Family to review the loss against its terms, exclusions, deductible and limit. Heavy rain can involve more than one water source, so the presence of an endorsement alone does not resolve every part of the claim.
Why was my American Family wind damage claim deductible so high?
American Family explains that wind/hail deductibles can differ from the standard property deductible. Check the amount or percentage on your declarations page and ask the adjuster to explain the calculation for this loss. Do not assume a metro-wide deductible.
Will American Family pay for mold from a storm leak?
Ask the carrier to identify the mold provisions and applicable limit for this storm loss. Do not assume that the water-damage decision guarantees payment for all mold work.
Water damage and mold claim documentation checklist
Use this checklist to organize your conversation with the adjuster. Coverage depends on your specific policy, endorsements and loss circumstances; confirm requirements with your carrier.
- Find your policy number, declarations page and relevant endorsements. Record the carrier contact and claim number once assigned.
- Record when you discovered the damage, the suspected source and the affected rooms. Keep a dated timeline of events and conversations.
- When safe, photograph the damage and affected belongings before cleanup. Keep original files and avoid entering unsafe areas for pictures.
- Keep receipts and records for emergency mitigation, drying equipment, temporary repairs and other related expenses.
- Request the inspection findings, moisture readings, drying logs, itemized scope and invoices from the restoration team.
- Ask the adjuster what additional documentation is required and what decisions need approval. Keep their written responses with your claim records.
Documentation supports review; it does not guarantee coverage or a payment timeline. Gateway can help organize your restoration records through insurance claims assistance. For emergency help, call (314) 947-3419, 24/7.
More American Family resources
Other American Family pages
on Gateway.
American Family storm and heavy rain claim. Call now.
Call Gateway, twenty-four seven, to describe the loss and confirm current crew availability and the next response step.
Policy and process sources (reviewed 2026-09-10): www.amfam.com. Coverage and claim handling depend on the applicable policy, endorsements and loss circumstances.